Hard Money Loans vs Traditional Financing for Real Estate Investors
Real estate investors have several financing options when purchasing, renovating, refinancing, or developing properties. Hard Money Loans and traditional financing are two commonly considered options, but they can serve very different investment strategies.
Understanding the differences between Hard Money Loans vs Traditional Financing can help investors evaluate funding speed, interest rates, loan terms, qualification requirements, property eligibility, financing costs, and exit strategies.
For investors purchasing rental properties, completing fix-and-flip projects, developing new construction, or expanding a real estate portfolio, selecting a financing structure that fits the transaction is an important part of the investment process.
What Are Hard Money Loans?
Hard Money Loans are generally short-term, real-estate-secured financing provided by private lenders or specialized lending companies.
Unlike many traditional mortgage programs, hard money underwriting may place greater emphasis on the property and transaction, along with factors such as purchase price, property value, renovation budget, borrower experience, liquidity, and exit strategy.
Hard money financing is commonly considered for:
- Fix-and-flip properties
- Investment property acquisitions
- Bridge transactions
- Renovation projects
- Time-sensitive purchases
- Properties that may not fit conventional financing guidelines
Key Features of Hard Money Loans
Funding Speed
One of the primary reasons investors consider Hard Money Loans is the potential for faster financing.
Depending on the lender, property, documentation, valuation, underwriting requirements, and transaction complexity, some hard money transactions may close more quickly than traditional mortgage financing.
This can be useful when an investor is working with a time-sensitive purchase or competitive acquisition.
Flexible Underwriting
Hard money lenders may evaluate the overall transaction rather than relying exclusively on conventional income documentation.
Depending on the program, the lender may consider:
- Property value
- Purchase price
- Renovation costs
- Borrower experience
- Available liquidity
- Investment strategy
- Exit strategy
Higher Financing Costs
Hard money financing generally carries higher borrowing costs than many traditional mortgage products.
Investors should evaluate the complete cost of the loan, including:
- Interest rate
- Points
- Origination fees
- Closing costs
- Loan term
- Extension fees
- Draw fees
- Prepayment provisions
The total cost of financing should be compared with the property’s projected investment return.
Advantages and Considerations of Hard Money Loans
Potential Advantages
- Faster access to capital for qualifying transactions
- Flexible underwriting structures
- Useful for properties requiring renovation
- Can support certain time-sensitive acquisitions
- May accommodate transactions that do not fit conventional guidelines
Potential Considerations
- Interest rates may be higher
- Loan terms are generally shorter
- Points and other fees may apply
- A realistic exit strategy is important
- The property serves as collateral for the loan
What Is Traditional Financing?
Traditional financing generally refers to mortgage financing provided by banks, credit unions, mortgage companies, and other financial institutions.
Traditional mortgage underwriting commonly considers the borrower’s:
- Credit history
- Income
- Assets
- Liabilities
- Debt obligations
- Employment
- Property characteristics
- Ability to repay
Traditional financing may be appropriate for certain investors seeking longer-term ownership and eligible investment-property financing.
Key Features of Traditional Financing
Longer Repayment Terms
Traditional mortgage programs may offer repayment periods such as 15 or 30 years, depending on the program.
Longer repayment periods can create a different monthly payment structure compared with short-term investment financing.
Potentially Competitive Interest Rates
Traditional financing can provide competitive interest rates for qualified borrowers and eligible properties.
However, actual rates vary based on market conditions, credit profile, loan amount, loan-to-value ratio, property type, occupancy, loan program, and other factors.
More Extensive Documentation
Traditional financing generally requires more detailed documentation and underwriting.
Borrowers may be asked to provide:
- Income documentation
- Bank statements
- Asset information
- Credit information
- Tax documents
- Employment information
- Existing debt information
- Property documentation
Requirements vary by lender and loan program.
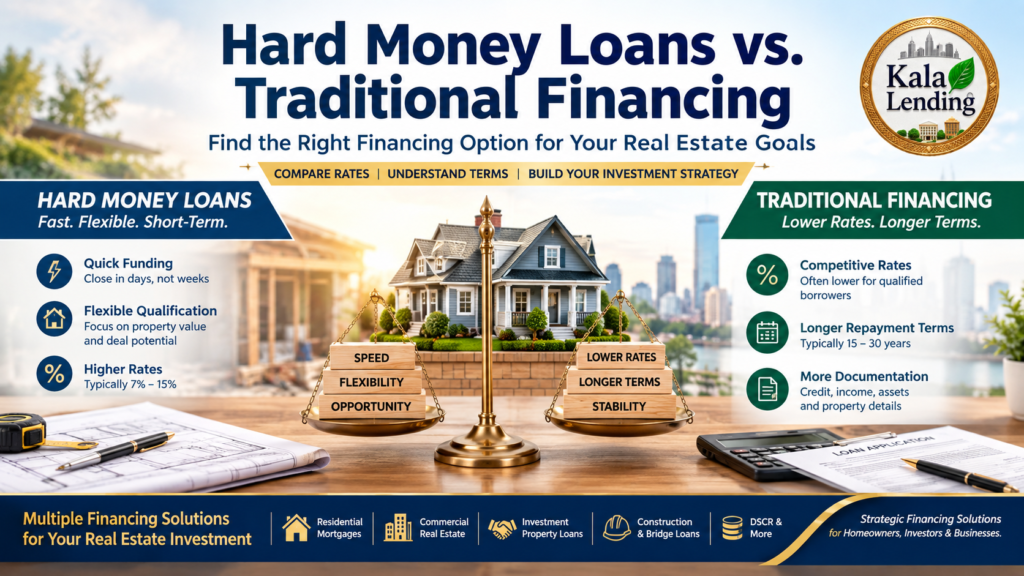
Hard Money Loans vs Traditional Financing: Key Differences
When comparing Hard Money Loans vs Traditional Financing, investors should evaluate the entire financing structure rather than focusing only on the interest rate.
| Factor | Hard Money Loans | Traditional Financing |
|---|---|---|
| Typical Loan Term | Short term | Often long term |
| Funding Speed | May be faster | Generally more extensive processing |
| Underwriting | Property/deal focused | Borrower and property focused |
| Interest Cost | Generally higher | Often lower for qualified borrowers |
| Documentation | May be more flexible | Typically more extensive |
| Common Uses | Fix & flip, bridge, renovation | Long-term ownership and eligible purchases |
| Exit Strategy | Particularly important | Depends on transaction |
| Flexibility | Often more flexible | Program-specific |
Actual interest rates, fees, terms, leverage, qualification requirements, and closing timelines vary by lender and transaction.
When to Consider Hard Money Loans
Investors may consider Hard Money Loans when speed, flexibility, or property characteristics make short-term financing appropriate.
Fix-and-Flip Properties
Fix-and-flip investors often need financing for both property acquisition and renovations.
A typical strategy involves purchasing a property, completing improvements, and then selling or refinancing after the project is completed.
Before proceeding, investors should calculate:
- Purchase price
- Renovation budget
- Financing costs
- Holding costs
- Property taxes
- Insurance
- Expected after-repair value
- Selling costs
- Contingency reserves
- Expected exit timeline
Time-Sensitive Acquisitions
Some real estate purchases have short closing deadlines.
When timing is critical, investors may explore financing options designed to provide quicker access to capital, subject to lender underwriting and documentation.
Properties Requiring Renovation
Properties requiring significant repairs may not fit every traditional mortgage program.
Specialized investment-property financing may provide an alternative depending on the property’s condition and transaction structure.
Bridge Financing
Investors may use bridge financing when they need short-term capital while planning to sell the property, refinance, complete improvements, or transition to permanent financing.
When Traditional Financing May Be Considered
Traditional financing may be considered by investors who intend to hold qualifying properties for the long term and meet the applicable lender requirements.
Potential applications include:
- Long-term rental properties
- Eligible investment properties
- Portfolio expansion
- Qualified property refinances
- Long-term real estate ownership
Investors should evaluate projected rental income, debt service, taxes, insurance, maintenance, vacancy, property management, reserves, and other operating expenses.
Other Real Estate Financing Strategies
Investors do not have to limit their analysis to traditional mortgages or Hard Money Loans.
Depending on the transaction, additional financing structures may include:
DSCR Rental Loans
Debt Service Coverage Ratio, or DSCR, financing can be designed for qualifying investment properties and may place significant emphasis on the property’s rental income and debt-service characteristics.
DSCR financing can be useful for certain investors building rental portfolios, subject to program and lender requirements.
Fix-and-Flip Financing
Fix-and-flip financing can provide capital for purchasing and renovating properties intended for resale.
Investors should carefully analyze the entire project budget and expected exit value before committing to financing.
Bridge Loans
Bridge loans can provide short-term financing for qualifying investment-property transactions where the borrower expects to sell, refinance, or transition to another financing structure.
Ground-Up Construction Financing
Investors and developers pursuing new construction can explore financing designed around land, construction costs, project timelines, borrower experience, and projected property value.
Multifamily and Commercial Financing
Multifamily and commercial properties may require financing structures tailored to the property’s size, income, occupancy, operating performance, and business plan.
Common Misconceptions About Hard Money Loans
“Hard Money Loans Are Only for Poor Credit”
Not necessarily.
Experienced real estate investors may use Hard Money Loans because they need speed, flexibility, renovation financing, or a transaction structure that differs from conventional underwriting.
Credit may still be considered, but it is not necessarily the only factor in every hard money transaction.
“All Hard Money Lenders Have the Same Terms”
Hard money terms can vary considerably between lenders.
Investors should compare:
- Interest rate
- Points
- LTV/LTC
- Fees
- Loan term
- Draw procedures
- Extension provisions
- Prepayment requirements
- Closing costs
Comparing the complete financing structure can provide a better understanding of the actual cost of capital.
Common Misconceptions About Traditional Financing
“You Need Perfect Credit”
Traditional lenders generally evaluate credit as part of their underwriting process, but requirements vary by program and lender.
A borrower does not necessarily need perfect credit to qualify for every traditional financing program.
“Traditional Financing Always Takes Too Long”
Traditional financing may involve more documentation and underwriting, but processing times can vary.
Having complete documentation and working with an experienced lending team can help make the process more efficient.
How to Evaluate Your Financing Options
There is no single financing structure that fits every real estate transaction.
Before selecting financing, investors should evaluate:
- Purchase price
- Current property value
- Renovation budget
- Required leverage
- Interest rate
- Points and fees
- Monthly debt service
- Loan term
- Prepayment provisions
- Closing timeline
- Rental income
- Reserves
- Exit strategy
- Expected investment return
This analysis can help investors understand how financing affects the overall economics of a real estate investment.
Hard Money Loans and Real Estate Investment Strategy
For investors considering Hard Money Loans, the most important consideration is not simply whether the interest rate is higher or lower than another financing option.
Investors should consider whether the financing structure fits the property, investment timeline, capital requirements, projected return, and exit strategy.
For a fix-and-flip project, financing speed may be particularly important. For a long-term rental, loan term, payment structure, rental income, and cash flow may receive greater attention.
Every transaction is different.
Kala Lending LLC: Real Estate Financing Solutions
Kala Lending LLC provides Strategic Financing Solutions for Homeowners, Investors & Businesses across the United States.
Our financing solutions may include:
- Residential Mortgages
- DSCR Rental Loans
- Investment Property Loans
- Fix & Flip Financing
- Bridge Loans
- Cash-Out Refinance
- Ground-Up Construction Financing
- Multifamily Financing
- Commercial Real Estate Financing
- Rental Portfolio Financing
Kala Lending LLC works with qualified U.S. Citizens, Permanent Residents, and Foreign Investors, subject to applicable lender and program requirements.
Transparent From PRE-Loan to Funding
At Kala Lending LLC, we believe borrowers and referral partners should receive clear communication throughout the financing process — from PRE-Loan to Funding.
Our approach emphasizes transparency regarding available loan programs, requirements, terms, and broker compensation.
We do not position our service around hidden fees added on top of our disclosed broker compensation.
Every transaction remains subject to applicable lender guidelines, borrower qualifications, property eligibility, underwriting, valuation requirements, and final approval.
Compare Your Real Estate Financing Options
Whether you are purchasing an investment property, financing a fix-and-flip project, refinancing a rental property, developing new construction, or expanding a multifamily or commercial portfolio, understanding your financing options is an important step.
Hard Money Loans and traditional financing serve different purposes. The appropriate financing structure depends on the specific property, borrower, investment strategy, financing requirements, and exit plan.
If you are considering financing for a U.S. real estate investment, contact Kala Lending LLC to explore potential financing solutions.
Get Started With Kala Lending LLC
🌐 Website: www.kalalending.com
📧 Loan Inquiries: fundings@kalalending.com
📞 Phone: (808) 278-6464
Kala Lending LLC
Strategic Financing Solutions for Homeowners, Investors & Businesses.
Disclaimer: Loan programs, interest rates, fees, LTV requirements, eligibility guidelines, and closing timelines vary by lender, borrower, property, market conditions, and transaction. This article is for informational and marketing purposes only and does not constitute a commitment to lend or a guarantee of financing.