Real Estate Investment Strategy in Today’s 7% Rate Market
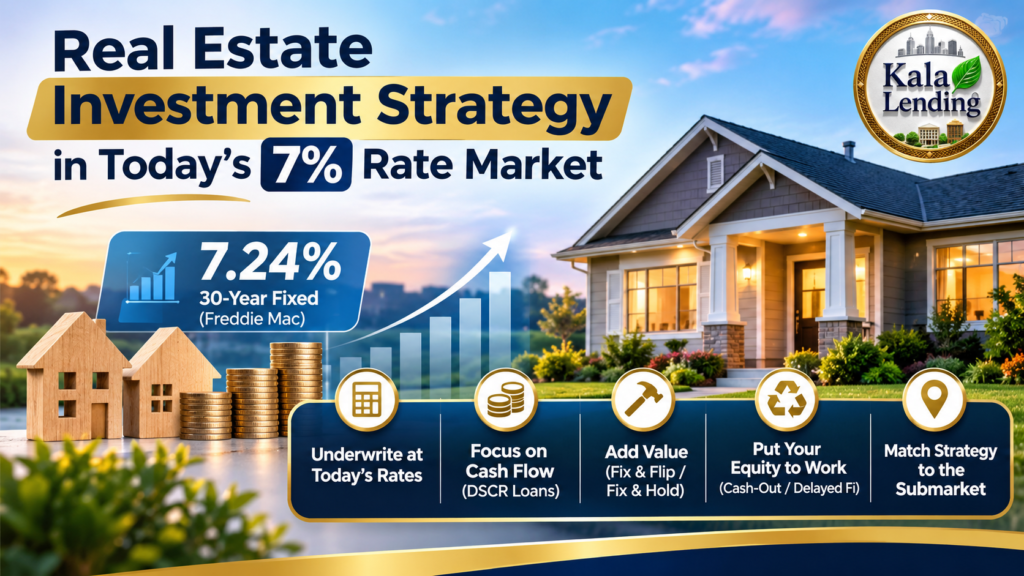
A smart real estate investment strategy looks different when 30-year rates sit above 7%. Freddie Mac’s latest survey showed the 30-year fixed rate at 7.24%, compared with 6.17% a year earlier. Deals that worked 18 months ago may not work now, but there is still opportunity for investors who plan carefully. Here is a five-step framework.
Real Estate Investment Strategy Starts With the Market You Have
Know today’s conditions before you buy anything.
- More inventory: Homes for sale rose to 1.60 million, up 4.6% from a year ago and the highest level since November 2019, equal to a 4.8-month supply.
- Slower sales: Sales remain near record lows, so buyers have more room to negotiate.
- Future supply squeeze: Builder confidence is at a 14-year low. Fewer starts today can mean tighter supply in 2027 and 2028.
- Rate risk: The Fed held rates on October 28, but economists say another hike is possible in December if inflation doesn’t improve.
The takeaway is that sellers are more flexible, financing is expensive, and rates may not fall soon.
Step 1: Underwrite at Today’s Rates
Don’t buy on the hope that rates will drop. One analysis advises making sure each deal works at about 7.3%, and treating any later rate drop as upside, not the plan.
On a $300,000 loan, a one-point difference in rate changes the monthly principal and interest by roughly $200. That is our own estimate, but it shows how small rate changes affect cash flow. If a deal only works at 6%, skip it.
Use the larger inventory to your advantage. Ask for price cuts, repair credits or seller-paid rate buydowns.
Step 2: Build Your Real Estate Investment Strategy Around Cash Flow
With prices flat in many areas, rental income matters more than appreciation. A DSCR loan qualifies you on the property’s rent, not your tax returns. Some lenders are currently offering 30-year fixed DSCR rates starting around 7.125%. Rates vary by lender and borrower profile.
To improve your DSCR:
- Aim for a ratio above 1.2.
- Lower insurance costs, reduce leverage, and choose properties with higher rent-to-price ratios.
- Get a quote on a DSCR purchase loan before you make offers, so you know your limits.
Step 3: Add Value Where Others Pass
Homes that sit on the market longer often need work, and that is where short-term financing helps. Bridge loans let you close fast, and fix and flip loans fund both purchase and renovation. If you plan to rent after the rehab, a fix and hold loan can bridge you into permanent financing.
Short-term money is costly, though. Hard money at 9% to 13% punishes any slip in your timeline, so keep a reserve fund and a clear exit for every property. A common exit is refinancing into a DSCR loan once the property is rented.
Step 4: Put Your Equity to Work
If you own properties with built-up equity, a cash-out refinance can fund your next down payment. If you bought with cash, delayed financing may let you recover your capital. A rate and term refinance makes sense only if it meaningfully lowers your current rate. Run the numbers on closing costs before you decide.
Step 5: Match Strategy to the Sub-market
National averages hide big differences. One mid-year outlook suggested a cash-flow strategy in loosening metros like Louisville and Cleveland, and a rent-growth strategy in tight coastal markets. It also noted that rents fell in oversupplied markets such as North Port, Austin and Denver. Even in stable cities, leasing can slow. In Charlotte, single-family rentals took about 11% longer to lease than a year earlier.
Before you buy, check local days on market, rent trends, insurance and property taxes. Then build a bench of lenders: a hard money lender, a local bank or credit union, and a DSCR or private-money partner.
Risks to Plan For
- Vacancy: budget for at least a few weeks of vacancy per year.
- Insurance and taxes: these can erode a thin DSCR quickly.
- Rate volatility: another Fed hike could push borrowing costs higher.
- Over-leverage: keep reserves of several months of payments.
Final Thoughts
A sound real estate investment strategy in this market comes down to five habits: underwrite conservatively, favor cash flow, add value, recycle equity, and know your sub-market. For more on where rates stand, read our mortgage rates today update.
Ready to move? Apply with Kala Lending or contact our team to match your goals with the right program. You can also browse more investor guides on the Kala Lending blog.
Disclaimer: This article is general information, not financial, tax or legal advice. Rates and terms vary by lender, property and borrower. Figures cited come from third-party sources and are not Kala Lending offers.