Mortgage Rates Today: 30-Year Near 7.3% as Fed Hike Looms
Mortgage rates today moved higher as the week opened. One daily survey puts the average 30-year purchase rate at 7.27%, and Mortgage Research Center shows 7.32%, up 0.29 percentage points from a week earlier. Sources differ, but the direction is the same. Here is what drove the move and what it means for homebuyers, investors and business owners.
Mortgage Rates Today at a Glance
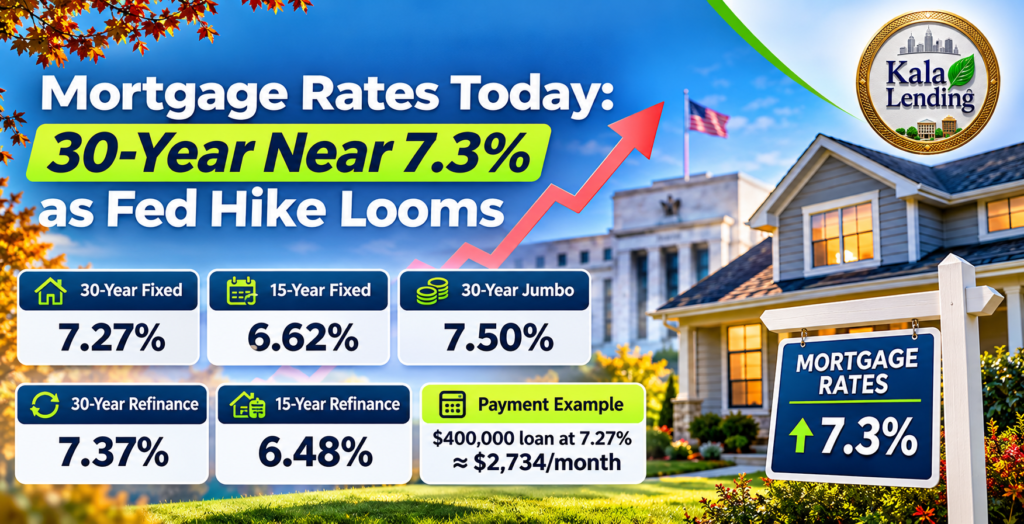
- 30-year fixed: about 7.27%, with the 15-year fixed near 6.62%
- 30-year jumbo: 7.50%
- 30-year refinance: 7.37%, with the 15-year at 6.48%
- Payment example: a $400,000 loan at 7.27% costs about $2,734 a month in principal and interest
Freddie Mac’s weekly survey looks calmer because it was released before the latest bond move. It showed the 30-year average falling for a fourth straight week to 7.11%. That reading is already stale.
Why Mortgage Rates Are Rising Again
Mortgage pricing follows the 10-year Treasury yield more closely than the Fed’s policy rate. This week the yield climbed 29.4 basis points to 5.152%, its largest weekly increase in 19 months, after hotter-than-expected inflation. October CPI rose 0.4% month over month, with core CPI up 0.3%, both above forecasts. The yield is still below its 52-week high of about 5.31% on October 5.
The Fed Is Now Part of the Story
The Fed raised rates in September to 3.75%–4%, and markets now price a December 8–9 increase as very likely. Governor Waller has said a half-point hike could be justified. A Fed hike does not directly set your loan rate, but it suggests borrowing costs could stay high for longer.
Demand Shows Borrowers Are Rate-Sensitive
When rates eased, borrowers responded. Mortgage applications rose 6.2% in the week ending November 6, with purchase applications up 8%. Purchase demand still ran 18% below last year. Homeowners also hold a record $17.5 trillion in equity. That keeps interest alive in a cash-out refinance for owners who want to tap equity without selling.
What Investors and Borrowers Can Do Now
- Weigh refinance goals carefully. A rate and term refinance only makes sense if the new rate beats your current one after closing costs.
- Qualify on property income. Rental investors can look at a DSCR loan, which uses rental income rather than personal income. Buyers can also review DSCR purchase loans.
- Use short-term financing for fast deals. Bridge loans and fix and flip loans can help when you plan to renovate and sell or refinance later.
- Compare total cost, not just the rate. Look at APR, points, fees and prepayment terms side by side.
- Watch this week’s data. Housing starts and the MBA application report arrive Wednesday, with Fed minutes also due this week.
Talk to Kala Lending About Your Next Loan
Averages are not offers, and your credit, property and loan structure decide your actual rate. Kala Lending, LLC has helped borrowers since 2009 with real estate and business financing. Explore our full list of loan services, learn about our team, read more market updates on the Kala Lending blog, then apply now or contact us for a consultation.
Rates are national averages from third-party sources as of November 16, 2026. They are not Kala Lending offers, are subject to change, and are not financial advice.