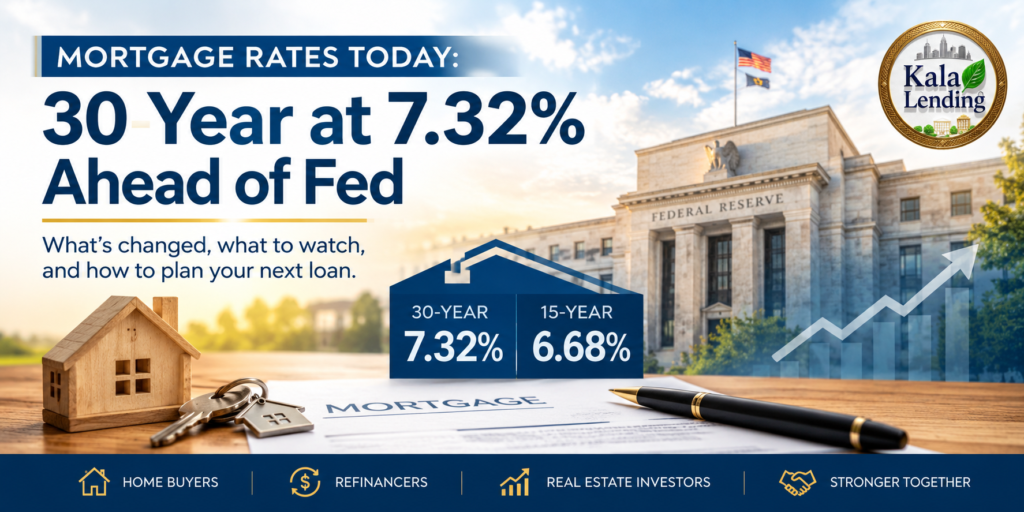
Mortgage rates today are hovering near 7.3% for a 30-year fixed loan. That is a small break for buyers and investors just as the Federal Reserve opens a two-day meeting. Here is what changed this week, what to watch on Wednesday, and how to plan your next loan.
Mortgage Rates Today: Where the Averages Stand
Freddie Mac reports the 30-year fixed-rate mortgage averaged 7.32% as of October 22, down from 7.40% the week before. The 15-year fixed averaged 6.68%, down from 6.71%. Rates are still well above last year, when the 30-year averaged 6.19% and the 15-year 5.44%.
Daily surveys show a similar picture. Mortgage News Daily put its 30-year fixed index at 7.33% on October 26, unchanged from the prior session. Bank-rate’s national average was 7.36%, down 0.11 points from the week before. Your own quote will differ based on credit score, down payment, loan type and lender.
Why the Fed Meeting Matters for Mortgage Rates
The Fed raised rates by a quarter point to 3.75%–4% in September, its first hike since 2023, and is expected to hold at its October 28 meeting. Markets still see a high chance of another hike by the December 8–9 meeting.
The Fed doesn’t set 30-year mortgage rates directly. Mortgage rates follow Treasury yields and the economic outlook, and the 10-year yield has been near 5%, keeping the 30-year rate close to 7.4%. Inflation is part of the pressure. September CPI rose 3.7% year over year, above forecasts, and core inflation reached 2.6%.
If the Fed holds and signals that rates stay higher for longer, mortgage rates could drift up. A softer tone could pull yields, and mortgage rates, lower.
Housing Market Snapshot
The housing market is still moving, but slowly. Existing-home sales rose 1.5% in September to a 3.99 million annual pace, but were down 2.2% from a year earlier. The median price hit $417,500, up 1.3% year over year, the 39th straight month of annual gains.
Buyers do have more options. Inventory reached 1.60 million homes, a 4.8-month supply, up from 4.5 months a year earlier. NAR’s chief economist said higher inventory and longer days on market give buyers more negotiating power.
What Mortgage Rates Today Mean for Buyers and Refinancers
- Homebuyers: Plan your budget around current rates, not hoped-for ones. More inventory and softer seller leverage can offset some of the rate pain, so negotiate on price and closing costs.
- Refinancers: With 30-year rates above 7%, a rate-and-term refinance only makes sense if your current rate is meaningfully higher. If you need cash for repairs or a down payment, a cash-out option may fit better.
- Rate shoppers: Compare multiple offers. National averages can sit well above the best offers available to strong borrowers.
What Today’s Rates Mean for Real Estate Investors
Investors face the same rate environment, but the numbers work differently. Rental income, not personal income, can drive approval on a DSCR loan that qualifies you with rental income. If you’re buying, see DSCR purchase loans. If you already own, compare a cash-out refinance with a rate and term refinance to see which fits your goals.
For short-term projects, bridge loans such as fix and flip loans can fund the purchase and rehab, and you can refinance into longer-term financing later.
The Bottom Line
Mortgage rates today are slightly lower but still elevated, and Wednesday’s Fed decision could move them either way. Watch Treasury yields and the Fed’s tone, and keep your paperwork ready so you can act when a good opportunity comes up.
Ready to explore your options? Start your loan application or contact the Kala Lending team for personalized guidance. For more updates, visit the Kala Lending blog.
Disclaimer: This article is for informational purposes only and is not financial advice. Rates are national survey averages, not offers from Kala Lending, and your rate will vary. Loan programs and availability are subject to underwriting and state licensing.