Mortgage Rates Today: 30-Year Rates Hit One-Month Low
Mortgage rates today are lower than they were a week ago. The average 30-year fixed rate is about 7.09%, according to Mortgage Research Center data reported by Forbes Advisor, and that is a one-month low. The decline is modest, but it is the first real relief for buyers and refinancers after weeks of rates above 7%. Here is what is driving the move and what it means for your next loan.
Mortgage Rates Today: Where the Numbers Stand
Rates vary by source and lender, but every major tracker shows a decline on Thursday:
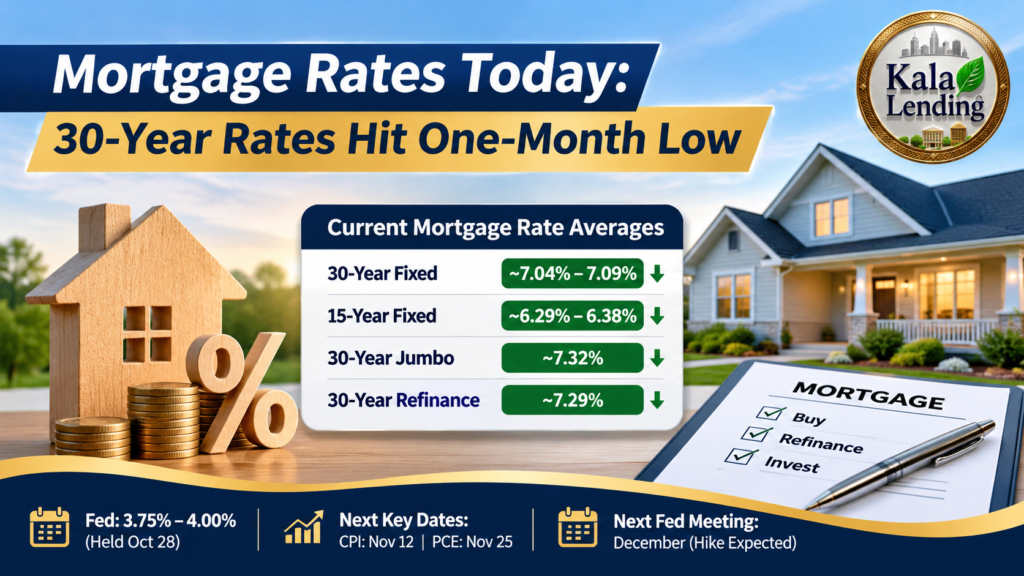
- 30-year fixed: about 7.04% to 7.09%, down roughly 0.13 percentage points from last week (NerdWallet, Zillow via Yahoo Finance, Forbes Advisor)
- 15-year fixed: about 6.29% to 6.38%
- 30-year jumbo: about 7.32%, down 0.15 points from a week ago
- 30-year refinance (Zillow): 7.29%, down 22 basis points from last week’s 7.51%
Freddie Mac’s weekly survey is the benchmark most people cite. It showed the 30-year fixed at 7.24% on October 29, down from 7.32% the week before. That is still about a full percentage point above where it stood a year ago.
Why Rates Are Falling: The Fed and the 10-Year Treasury
The Federal Reserve held its benchmark rate at 3.75% to 4% at its October 28 meeting, in a 10-2 vote. That was widely expected, and the Fed does not set mortgage rates directly. Mortgage rates follow the 10-year Treasury yield, and that yield has been drifting lower in recent weeks.
Markets are not expecting relief from the Fed itself. According to CME Group’s FedWatch tool, about 77% of traders expect another 25-basis-point hike in December. The Fed raised rates in September. Lenders appear to have priced much of that expectation in already. Fed Chair Kevin Warsh has also announced fewer FOMC votes in the coming years, which puts more weight on each remaining meeting.
What This Means for Homebuyers and Refinancers
Lower rates are not yet bringing buyers back. The Mortgage Bankers Association reported that total mortgage applications fell 1.2% last week. Purchase applications dropped 2% and are 19% lower than a year ago. Refinance share rose to 39.8% of applications, and adjustable-rate mortgages made up 11.4% of activity, the highest share since September 2025.
Here is what a small rate drop is worth. On a $300,000 loan, the 0.13-point decline cuts the monthly principal-and-interest payment by roughly $26 (our estimate, excluding taxes and insurance). That is helpful but not trans-formative. Borrowers who need to move should compare options now rather than wait for a bigger drop.
If you already own a home, a rate-and-term refinance could make sense if your current rate is meaningfully higher than today’s. A cash-out refinance lets you tap equity at today’s rates. Kala Lending offers both through its Rate & Term Refinance and Cash-Out Refinance programs.
Trump’s Housing Executive Order: What Changed
President Trump recently signed an executive order aimed at lowering housing finance costs. It includes:
- Proactive mortgage insurance cancellation by servicers of conventional loans
- A permanent title insurance waiver program through the FHFA
- Reduced rates on some government-backed loans
- A manufactured housing task force
Mortgage lender Hector Amendola of SimplyPMG called the mortgage insurance provision “a bigger deal than people think.” Borrowers who have reached the statutory threshold could free up monthly cash. Details of implementation are still to come, so check with your serviced.
Investors: Mortgage Rates Today Still Matter
Investors feel high rates more than anyone, because financing costs hit cash flow directly. Kala Lending’s DSCR loans qualify borrowers on rental income rather than personal income. They work for new purchases and for delayed financing. Short-term projects can use bridge loans, including fix and flip loans, which let investors finance now and refinance into longer-term debt if rates fall.
For broader needs, see our real estate business loans. New to financing? Read our guide to direct mortgage lenders or how to secure your home loan.
What to Watch Next
Three events could move mortgage rates today’s levels in the weeks ahead:
- November 12: the CPI inflation report
- November 25: the PCE inflation report
- December: the next Fed meeting, where a hike is currently expected
Softer inflation data could pull rates lower. Hot data could erase this week’s gains. Rates can change daily, so locking in a rate when you find one that fits your budget is often wiser than trying to time the market.
Bottom Line
Mortgage rates today are at a one-month low, but they remain elevated and the Fed outlook is uncertain. Whether you are buying, refinancing, or investing, the best move is to compare real quotes for your situation. Ready to see your options? Apply now or contact our team for a personalized quote.
Disclaimer: Rates shown are national averages from third-party sources and are not Kala Lending offers. Your rate depends on credit, loan type, down payment, and property. This article is for informational purposes only and is not financial advice. See our Disclaimer.