Home Sales 16-Year Low: What 7.11% Mortgage Rates Mean
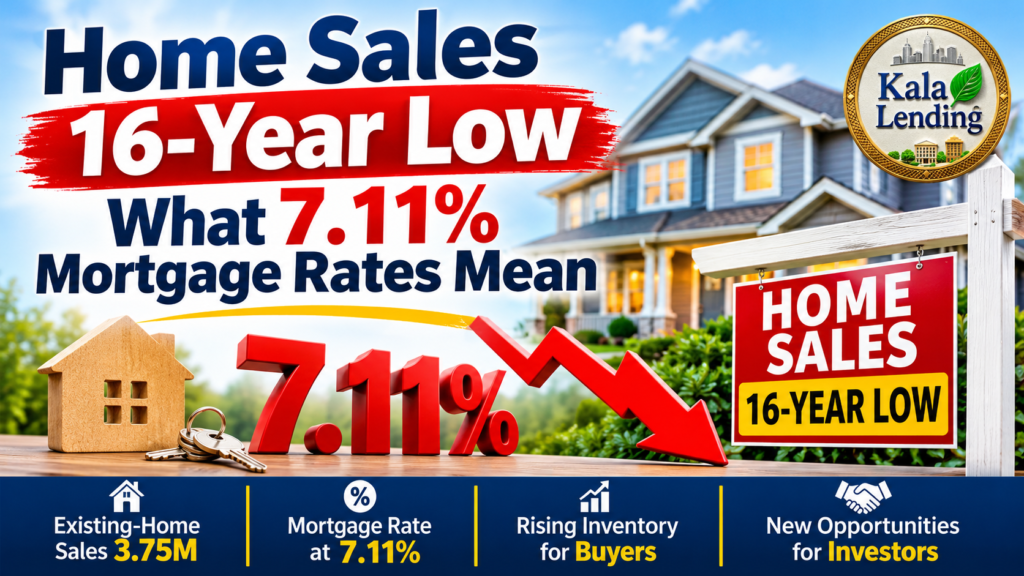
The home sales 16-year low reported by the National Association of Realtors on November 12 is the clearest sign yet that 7% borrowing costs are freezing the US housing market. Existing-home sales fell 5.5% in October to a 3.75 million annual pace, the weakest since August 2010. Yet Freddie Mac says mortgage rates have now dropped four weeks in a row. Here is what that mixed picture means for buyers, sellers, and real estate investors.
Key takeaways
- Existing-home sales hit 3.75 million (annualized), down 8.8% from a year ago.
- Freddie Mac’s 30-year fixed rate averaged 7.11%, a seven-week low.
- A hot October inflation report has pushed daily rates back up.
- Rising inventory is creating negotiating room for prepared investors.
What the Home Sales 16-Year Low Really Tells Us
NAR’s October report shows a market stuck in a standoff. Sales fell in all four regions, and the West and South hit multi-year lows. The median price still rose 0.4% to $416,700, the 40th straight month of annual gains. Buyers are waiting for relief, and many sellers aren’t cutting prices enough to move.
Other numbers point the same way. Inventory climbed to 1.59 million homes, a 5.1-month supply, up from 4.4 months a year ago. Homes took a median of 35 days to sell. First-time buyers made up just 29% of purchases, and NAR’s affordability index slid to 100.7 from 107.3 a year earlier.
Mortgage Rates Today: Four Weekly Drops, Then a Hot CPI
Freddie Mac’s survey shows the 30-year fixed at 7.11%, down from 7.18%, and the 15-year at 6.45%. That is progress from the early-October peak, but rates are still well above last year’s 6.24%. On a median-priced home with 20% down, the principal-and-interest payment is about $2,240 a month. That is roughly $190 more than at last year’s rate (our estimate).
The relief may be short-lived. The Bureau of Labor Statistics reported on November 10 that consumer prices rose 0.4% in October, above forecasts. Core CPI rose 0.3% for the third month in a row. The 10-year Treasury yield, which mortgage rates tend to follow, jumped back toward 5%. Markets now fully expect the Fed to raise its 3.75%–4.00% target range at its December 8–9 meeting. A strong jobs report (165,000 new jobs, 4.1% unemployment) supports that view. Some daily trackers already show the 30-year fixed back near 7.26%.
Freddie Mac’s number looks backward over the past week’s applications. Today’s quote may be higher, so check a live rate before you plan around 7.11%. For more on the inflation side, read our breakdown of CPI and mortgage rates and the Fed hike odds and our recap of the third weekly mortgage rate drop to 7.18%.
What the Home Sales 16-Year Low Means for Real Estate Investors
A frozen sales market is frustrating, but it also shifts leverage. More inventory, longer time on market, and more price cuts give prepared buyers room to negotiate on price, repairs, and seller-paid rate buydowns. Reports on NAR data also show investors and second-home buyers taking a bigger share of sales than a year ago, at about 20%.
Higher rates do squeeze rental cash flow, so the financing structure matters more than ever:
- Buying and holding rentals: a DSCR loan qualifies you on the property’s rental income. DSCR purchase loans are built for acquisitions.
- Renovating and reselling: Fix & Flip loans and bridge loans offer speed when sellers want certainty.
- Pulling equity out of existing holdings: a cash-out refinance can fund the next purchase. If you only want to adjust your rate or term, see rate and term refinance.
- Bought with cash? Delayed financing can help you recover your capital after closing.
For a deeper strategy read, see Real Estate Investment Strategy in Today’s 7% Rate Market and What the Nov 6 Selloff Means for Investors.
Loan Limits: Watch the Late-November FHFA Announcement
The 2026 conforming loan limit is $832,750. FHFA is expected to publish the 2027 limits in late November, and several large lenders have already raised their own early limits to around $845,000. Early limits are lender-specific and carry risk if FHFA’s official number comes in lower. If your loan amount sits near the current ceiling, ask your lender how timing and pricing would change.
5 Moves to Make Before the December Fed Meeting
- Get a live rate quote instead of relying on weekly averages.
- Stress-test rental income at 7%+ rates before you make an offer.
- Negotiate seller concessions and rate buydowns while inventory is high.
- Compare total costs (fees, points, timeline), not just the headline rate.
- Line up pre-approval now, since rates could move after December 9.
The Bottom Line
The home sales 16-year low shows how much affordability has deteriorated, but the market isn’t one-sided. Buyers have more choices and leverage than at any point in recent years, while financing costs remain the main obstacle. Investors who stay liquid, structure loans carefully, and move quickly on good deals can still find opportunity.
Ready to explore your options? Apply now or contact the Kala Lending team for transparent, fast financing built for U.S. and foreign investors. You can also browse all our loan programs or read more market updates.
Disclaimer: This article is for informational purposes only and is not financial or legal advice. Rates and terms vary by borrower, property, and lender, and are subject to change. All loans are subject to underwriting approval.
Sources: Freddie Mac PMMS (Nov. 12, 2026); National Association of Realtors (Nov. 12, 2026); U.S. Bureau of Labor Statistics CPI and Employment Situation reports (Nov. 6 and 10, 2026); Federal Reserve October 2026 decision coverage; FHFA and lender loan-limit announcements.